Checking the tape - key takeaways from May 2024 CPI-U inflation
Eric Pachman
Published
June 12th 2024
Eric Pachman
Published
June 12th 2024
This morning the Bureau of Labor Statistics released the May 2024 Consumer Price Index for All Urban Consumers (CPI-U). Overall CPI-U was reported at 3.27% year-over-year (YoY) for May, down just nine basis points from 3.36% year-over-year last month.
As a reminder, Bancreek publishes two visualizations that can help you explore CPI-U in granular detail. Both of these visualizations have now been updated through May and are embedded below:
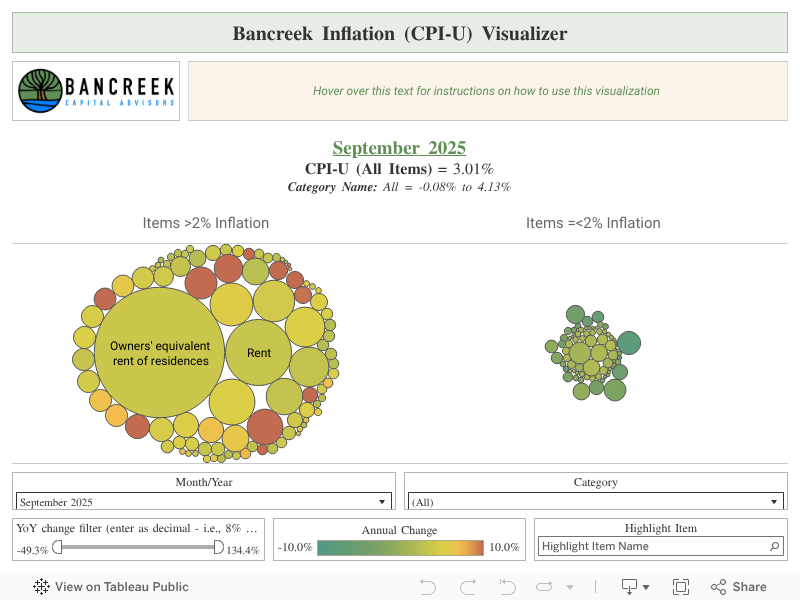
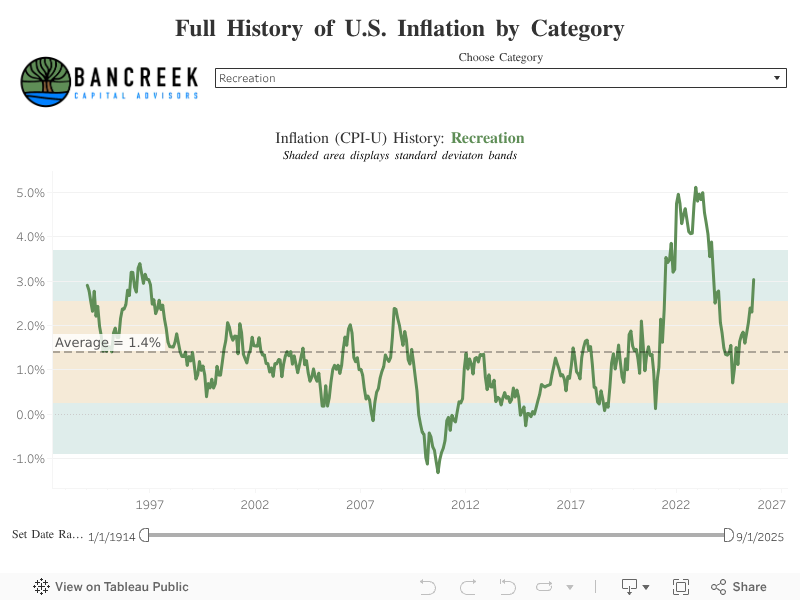
This post hopefully will further assist in your analysis of the moving parts underlying this month’s CPI-U print. Its goal is not to provide a comprehensive analysis of the nearly 180 items we track (that’s what the visualizations are for), but rather just to point to the most meaningful changes from one month to the next.
To perform this analysis, we track a measure we call “inflation impact,” which we calculate by multiplying each item’s YoY inflation by its weight in the prior year period. You can think of this as “weighted inflation” as opposed to the “unweighted inflation” that is more commonly reported by the media. Each month we take the weighted inflation of each item we track in CPI-U and then sum them up to overall CPI-U. Then we compare these weighted inflation numbers from one month to the next to see what drove the sequential increase or decrease. In this way, we can precisely identify the most significant drivers in the change in YoY CPI-U from one month to the next.
Again, in May 2024, overall YoY CPI-U declined by nine basis points. When we look at the change in item-level inflation impact from April to May, we see that the largest favorable move was once gain in Used cars and trucks, which shaved 7.3 basis points off YoY inflation alone. As shown in the chart below, the other items that were most favorable were Motor vehicle insurance (5.4 basis points favorable), and Owners' equivalent rent of residences (2.3 basis points favorable). This was partially offset by unfavorable moves in Gasoline (3.1 basis points) and Health insurance (2.7 bps).
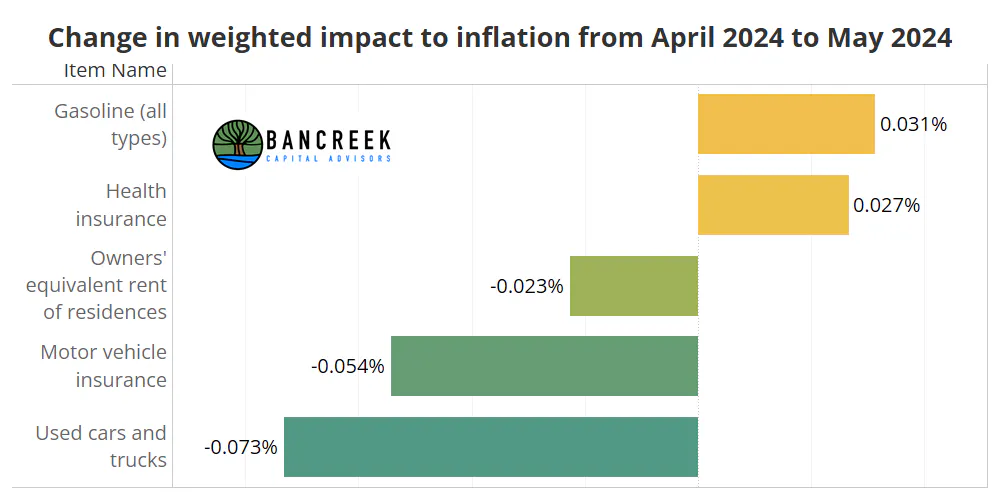
Source: Bancreek Capital Advisors, LLC
Note that the five items shown above all net to the nine basis point decline in YoY CPI-U from April to May. Of course, this does not mean that the inflation impact of the other 170+ items was flat from one month to the next. However, all other items had a change in inflation impact that was less than two basis points from one month to the next, and when summed together, they all conveniently netted to a zero inflation impact, simplifying the story down to just these five items.
So, let's take a look at these five items in more detail.
We believe it’s important to look at the changes in each of the largest favorable / unfavorable items in context of their historical volatility. To assist with this, the image carousel below shows the trend chart for each of the aforementioned items.
On further inspection of these charts, we see the movement in this month's main drivers as quite positive.
First off, Used cars and trucks inflation (down 9.3% YoY) is over one standard deviation below the mean now and has maintained meaningful deflation for well over a year now. So, it seems we can be pretty comfortable that the deflation in this significant item is more than "noise."
Second, we finally have seen a crack in the Motor vehicle insurance inflation machine! It declined from 22.6% inflation in April to 20.3% inflation in May. This is wonderful news for CPI-U, which due to the high weight and unprecedented recent inflation in Motor vehicle insurance has significant sensitivity to this single item.
Third, YoY OER inflation continued to moderate from one month to the next, dropping from 5.8% to 5.7%. Recall OER is the 800-lb gorilla of CPI-U, carrying a 25.5% weight of the entire inflation measure. So, to have good visibility of true moderation in CPI-U to the mid 2% range, we really need cooperation from housing. Sadly, when you look at OER's sequential month-over-month inflation, it went the wrong direction in May. In other words, shelter continues to be an issue.
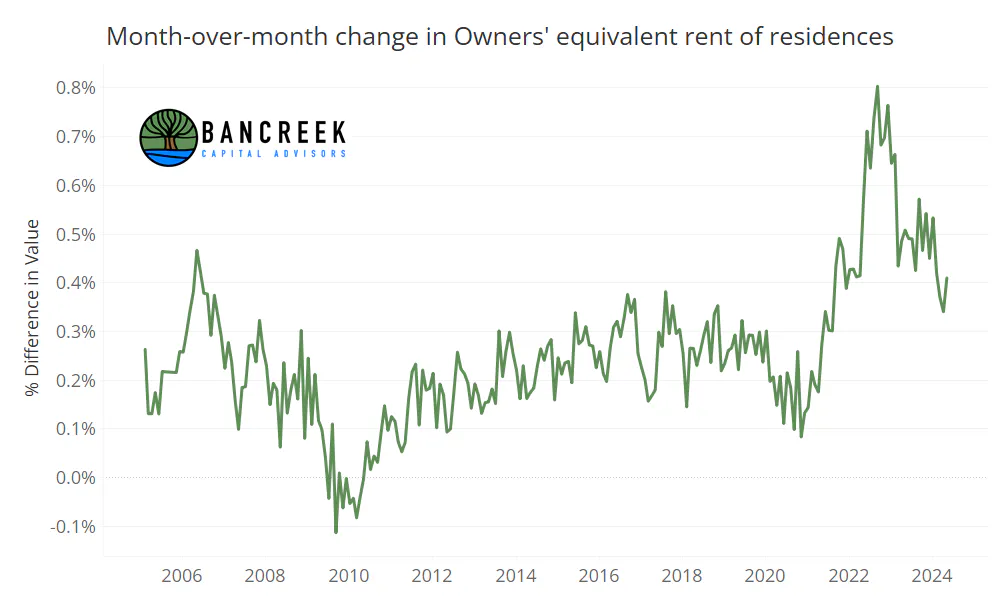
Source: Bancreek Capital Advisors, LLC
Turning to the unfavorable items, gasoline's change was largely insignificant when put in content of its historical volatility. So, not much to be concerned about with that item, in our view. However, Health insurance is a different story. This item was uncharacteristically deflationary last year, shaving more than 30 basis points off overall headline CPI-U towards the end of 2023. As shown below, sequential month-over-month inflation for this item is now rising again, quickly shrinking the YoY deflationary benefit CPI-U is getting from Health insurance. If the recent level of sequential inflation in this item continues, it's only a matter of time before Health insurance starts to act as a headwind to YoY CPI-U, rather than a tailwind as it's been over the past year.
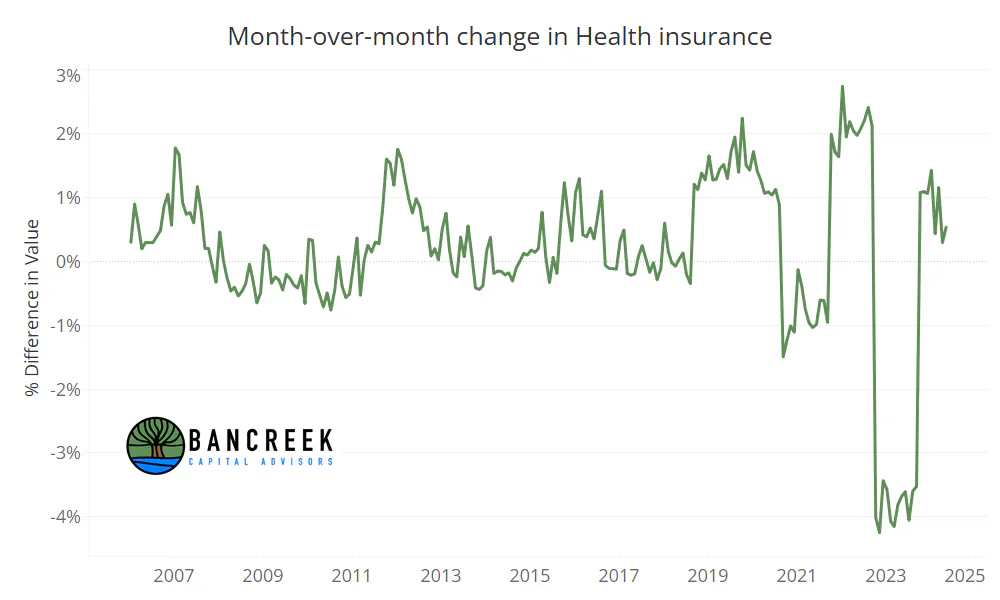
Source: Bancreek Capital Advisors, LLC
Summary
While YoY inflation only declined by nine basis points from April to May, when we look at the moving parts, we are quite encouraged. The biggest news of the month, in our view, was that Motor vehicle insurance finally broke to the downside. It was also comforting to see Used cars and trucks continue to post meaningful deflation.
On the flip side, for those that want better visibility of a glide path for CPI-U down to the mid-2% range, shelter really needs to moderate at a faster pace. This is especially true as we lose the deflationary benefit of health insurance throughout the year.
Have questions about market trends, investment strategies, or our research services? Reach out to our team.
Enjoying this post?
Tell others about it.

Bancreek's Actively Managed ETFs
If you are interested in learning more about Bancreek Capital Advisors' actively managed ETFs click the link below
Learn MoreMore articles like this
Fetching Related Posts
There are no other articles tagged with Research
